جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Margin period of risk؟

Definition 20.7 Markets I: The Ecosystem and Exchange-Traded Markets · الفصل 20 — Margin

The margin period of risk is the time assumed between a member’s last payment of variation margin and the moment its portfolio has been hedged or liquidated by the clearing house: the horizon of the initial-margin calculation. It is a day or two for liquid listed futures and longer for cleared swaps and illiquid products.

اقرأ في الفصل →
Definition 17.9 Rates, Credit, XVA and Risk · الفصل 17 — Counterparty Exposure

The exposure under a collateral agreement at tt is max⁡(Vt−Ct−δ,0)\max(V_t-C_{t-\delta},0), where δ\delta is the margin period of risk of One Quant Book 1: the collateral is the one agreed δ\delta earlier. The exposure is the move of the netting set’s value over δ\delta, plus the threshold and the minimum transfer amount.
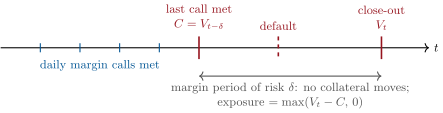
The margin period of risk: the last collateral received matches the value at the last successful call; between it and the close-out the counterparty posts nothing, and the value keeps moving. Schematic.
Figure 17.3. The margin period of risk: the last collateral received matches the value at the last successful call; between it and the close-out the counterparty posts nothing, and the value keeps moving. Schematic.
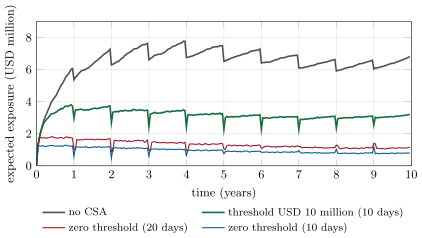
Expected exposure of the netting set without collateral and under three CSAs. A zero-threshold CSA flattens the profile to the value moves over the margin period of risk; doubling that period multiplies them by about √2; a threshold adds exposure up to its size. The teeth at each anniversary are the annual payments, which the lagged collateral does not yet reflect. Data: the chapter’s tutorial.
Figure 17.4. Expected exposure of the netting set without collateral and under three CSAs. A zero-threshold CSA flattens the profile to the value moves over the margin period of risk; doubling that period multiplies them by about 2\sqrt2; a threshold adds exposure up to its size. The teeth at each anniversary are the annual payments, which the lagged collateral does not yet reflect. Data: the chapter’s tutorial.

أمثلة

Example 17.10 (Collateralising the netting set)

Under a two-way CSA with zero threshold and a minimum transfer amount of USD 500 000, the netting set’s EE falls to a nearly flat USD 1.30 million at its peak and its PFE to USD 6.45 million with a margin period of risk of ten business days; the EPE over the life falls from USD 6.44 million to 0.95 million, 15% of the uncollateralised figure. With twenty days the peak EE is USD 1.83 million, 2\sqrt2 times higher; with a threshold of USD 10 million it is USD 3.81 million (Figure 17.4).

اقرأ في الفصل →