 Coach
The margin valuation adjustment (MVA) is the value of the cost of funding the initial margin a position requires over its life: .
Examples
Example 19.5 (MVA of the swap)
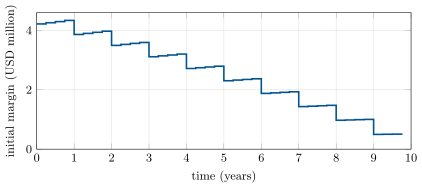
With Book 2’s sensitivity model, initial margin is 2.326 standard deviations of the swap’s value over ten days at a rate volatility of 7 basis points a day: USD 4.22 million today, falling as the swap’s DV01 runs off (Figure 19.2). Funding it at 80 basis points costs USD 175 217 over the swap’s life.