Tous les livres

Professionnel

Applis À propos Coach Connexion Commencer la lecture

Quantitative Finance · Glossaire

Qu'est-ce que « Margin valuation adjustment » ?

Definition 19.4 Rates, Credit, XVA and Risk · Chapitre 19 — Funding, Margin and Capital Adjustments

The margin valuation adjustment (MVA) is the value of the cost of funding the initial margin a position requires over its life: MVA=∫0T(sf−rIM) E[IM(t)] P(0,t) dt\mathrm{MVA} = \int_0^T(s_f-r_{\mathrm{IM}})\,\E[\mathrm{IM}(t)]\,P(0,t)\,dt.

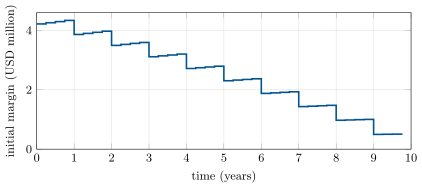
Expected initial margin of the ten-year swap under a sensitivity-based model: it starts at USD 4.22 million and falls with the swap’s remaining DV01. Its funding cost over the life is the MVA. Data: the chapter’s tutorial.
Figure 19.2. Expected initial margin of the ten-year swap under a sensitivity-based model: it starts at USD 4.22 million and falls with the swap’s remaining DV01. Its funding cost over the life is the MVA. Data: the chapter’s tutorial.

Exemples

Example 19.5 (MVA of the swap)

With Book 2’s sensitivity model, initial margin is 2.326 standard deviations of the swap’s value over ten days at a rate volatility of 7 basis points a day: USD 4.22 million today, falling as the swap’s DV01 runs off (Figure 19.2). Funding it at 80 basis points costs USD 175 217 over the swap’s life.

Lire dans le chapitre →