A strategy’s market beta is the slope of its returns on the market’s, , estimated by regression with an intercept, the alpha (Book 1, chapter 1); standard errors are HAC.
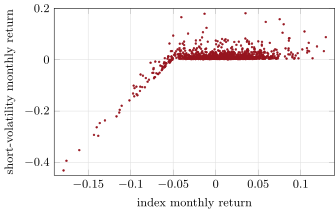
rs_perf.monthly_scatter. Coach
Iniciar sesión
Empezar a leer
Quantitative Finance · Glosario
A strategy’s market beta is the slope of its returns on the market’s, , estimated by regression with an intercept, the alpha (Book 1, chapter 1); standard errors are HAC.
rs_perf.monthly_scatter.