Todos os livros

Profissional

Apps Sobre Coach Entrar Começar a ler

Quantitative Finance · Glossário

O que é Market beta?

Definition 22.7 Research Craft: Predictors, Backtests, Measurement, Portfolios · Capítulo 22 — Performance Measurement

A strategy’s market beta is the slope of its returns on the market’s, β=Cov⁡(r,rm)/Var⁡(rm)\beta = \operatorname{Cov}(r, r_m)/\operatorname{Var}(r_m), estimated by regression with an intercept, the alpha (Book 1, chapter 1); standard errors are HAC.
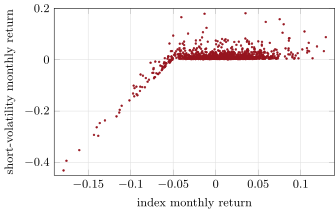
Monthly returns of the short-volatility strategy against the index, over 100 simulated years: a short put’s payoff, with daily betas of 0.98 on down days and 0.71 on up days. Data: rs_perf.monthly_scatter.
Figure 22.3. Monthly returns of the short-volatility strategy against the index, over 100 simulated years: a short put’s payoff, with daily betas of 0.98 on down days and 0.71 on up days. Data: rs_perf.monthly_scatter.
Ler no capítulo →
