Todos os livros

Profissional

Apps Sobre Coach Entrar Começar a ler

Quantitative Finance · Glossário

O que é Merton fraction?

Definition 9.9 Quantitative Methods · Capítulo 9 — Stochastic Control

The Merton fraction is π∗=(μ−r)/(γσ2)\pi^* = (\mu - r)/(\gamma\sigma^2).

Certainty-equivalent return of a constant fraction in equities for a CRRA investor with = 3 (= 7\%, r = 2\%, = 18\%): a parabola peaking at the Merton fraction (left dot, 51.4%), flat enough that 60% (right dot) costs only 3.6 bp a year. The Kelly fraction, optimal for = 1, is 154%. Data: closed form, the chapter’s tutorial.
Figure 9.1. Certainty-equivalent return of a constant fraction in equities for a CRRA investor with γ=3\gamma = 3 (μ=7%\mu = 7\%, r=2%r = 2\%, σ=18%\sigma = 18\%): a parabola peaking at the Merton fraction (left dot, 51.4%), flat enough that 60% (right dot) costs only 3.6 bp a year. The Kelly fraction, optimal for γ=1\gamma = 1, is 154%. Data: closed form, the chapter’s tutorial.
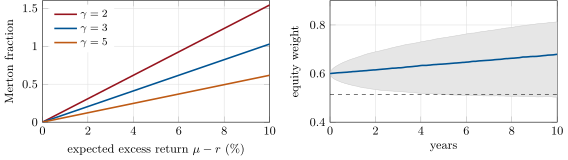
Left: the Merton fraction against the expected excess return, for three risk aversions (= 18\%): ten points of fraction per point of return at = 3. Right: the equity weight of a fund that starts at 60% and never rebalances, median and 10th–90th percentile band over 20 000 simulated paths, against the Merton fraction (dashed). Data: the chapter’s tutorial, seeded.
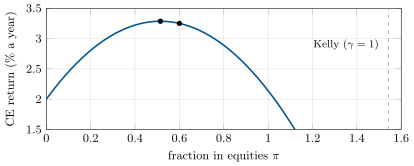
Figure 9.2. Left: the Merton fraction against the expected excess return, for three risk aversions (σ=18%\sigma = 18\%): ten points of fraction per point of return at γ=3\gamma = 3. Right: the equity weight of a fund that starts at 60% and never rebalances, median and 10th–90th percentile band over 20 000 simulated paths, against the Merton fraction (dashed). Data: the chapter’s tutorial, seeded.
Ler no capítulo →
