 Coach
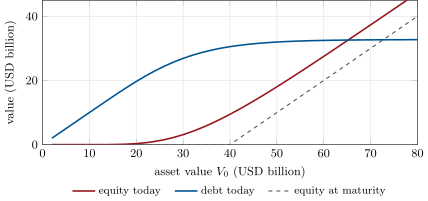
The Merton model takes assets following a geometric Brownian motion with volatility and one zero-coupon debt of face due at . At the shareholders receive and the creditors . Equity is a European call on the assets struck at the debt, priced by the Black–Scholes formula, and debt is the assets minus the equity:
उदाहरण
Example 14.3 (A leveraged firm)
An illustrative firm has equity worth USD 10 billion with a volatility of 50%, and debt of face USD 40 billion treated as due in five years; . The inversion gives assets of USD 40.69 billion with a volatility of 15.6%: the equity is more than three times as volatile as the assets because it is levered. The debt is worth USD 30.69 billion, a yield spread of 130 basis points, and the risk-neutral probability that the assets end below the face is 32.7%.