सभी किताबें

पेशेवर

ऐप्स परिचय Coach लॉग इन पढ़ना शुरू करें

Quantitative Finance · शब्दावली

Multicollinearity, variance inflation factor क्या है?

अन्य नाम: multicollinearity · variance inflation factor

Definition 16.4 Quantitative Methods · अध्याय 16 — Linear Models under Stress

Multicollinearity is near-linear dependence among the columns of the design. The variance inflation factor of regressor jj is VIFj=1/(1−Rj2)\mathrm{VIF}_j = 1/(1 - R_j^2), with Rj2R_j^2 the R2R^2 of regressing xjx_j on the other regressors.

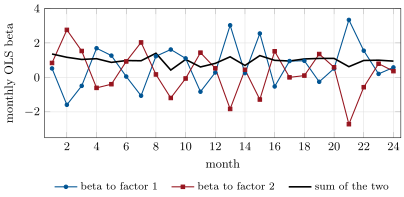
A stock’s betas to two factors with correlation 0.97, estimated each month from 21 daily returns (true values 0.6 and 0.4). The individual betas swing between -2.7 and 3.3; their sum stays near its true value of 1.0 (standard deviation 0.23). Data: the chapter’s tutorial, seeded.
Figure 16.1. A stock’s betas to two factors with correlation 0.97, estimated each month from 21 daily returns (true values 0.6 and 0.4). The individual betas swing between −2.7-2.7 and 3.33.3; their sum stays near its true value of 1.0 (standard deviation 0.23). Data: the chapter’s tutorial, seeded.
अध्याय में पढ़ें →