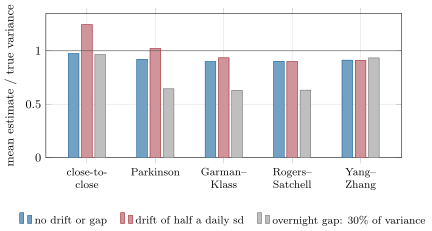
With H,L,O,C a day’s high, low, open and close, the Parkinson estimator of the daily variance is (lnH/L)2/(4ln2); the Garman–Klass estimator is 21(lnH/L)2−(2ln2−1)(lnC/O)2; the Rogers–Satchell estimator is ln(H/C)ln(H/O)+ln(L/C)ln(L/O). The Yang–Zhang estimator over n days adds the sample variance of overnight returns, k times that of open-to-close returns and 1−k times the average Rogers–Satchell term, with k=0.34/(1.34+(n+1)/(n−1)).
 Coach