
सभी किताबें

पेशेवर

ऐप्स परिचय Coach लॉग इन पढ़ना शुरू करें

Quantitative Finance · शब्दावली

Particle filter, sequential importance resampling क्या है?

अन्य नाम: particle filter · sequential importance resampling

Definition 19.9 Quantitative Methods · अध्याय 19 — State-Space Models and the Kalman Filter

A particle filter represents the filtering law of a state by a weighted sample of particles. Sequential importance resampling, the bootstrap filter of Gordon, Salmond and Smith (1993), propagates each particle through the state equation, weights it by the density of the new observation given the particle, and resamples in proportion to the weights; the average weight at each step estimates the one-step predictive density, and their product the likelihood.
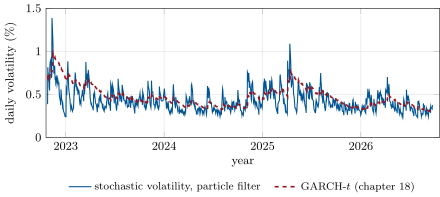
EUR/USD daily volatility over the last 1 000 ECB fixings to 23 September 2026: the particle-filtered stochastic-volatility estimate (= 0.9, _ = 0.4, 5 000 particles) and the GARCH-t conditional volatility. Data: ECB euro reference rates (source: ECB statistics).
Figure 19.5. EUR/USD daily volatility over the last 1 000 ECB fixings to 23 September 2026: the particle-filtered stochastic-volatility estimate (ϕ=0.9\phi = 0.9, ση=0.4\sigma_\eta = 0.4, 5 000 particles) and the GARCH-tt conditional volatility. Data: ECB euro reference rates (source: ECB statistics).
अध्याय में पढ़ें →