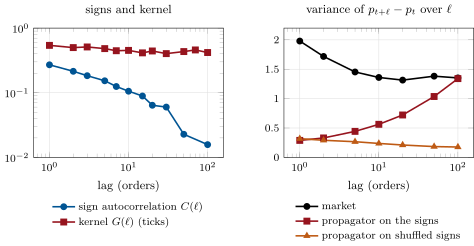
The propagator model writes the price before trade as the sum of the impacts of all past trades,
where the decay kernel (the propagator) is the impact of one trade trades later, independent of the others.
mx_prop.kernel_study. Coach
लॉग इन
पढ़ना शुरू करें
Quantitative Finance · शब्दावली
अन्य नाम: propagator model · decay kernel
The propagator model writes the price before trade as the sum of the impacts of all past trades,
where the decay kernel (the propagator) is the impact of one trade trades later, independent of the others.
mx_prop.kernel_study.