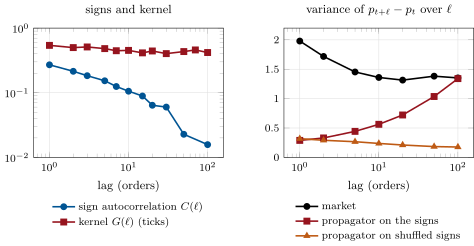
The propagator model writes the price before trade as the sum of the impacts of all past trades,
where the decay kernel (the propagator) is the impact of one trade trades later, independent of the others.
mx_prop.kernel_study. Pelatih
Masuk
Mulai membaca
Quantitative Finance · Glosarium
Dikenal juga sebagai: propagator model · decay kernel
The propagator model writes the price before trade as the sum of the impacts of all past trades,
where the decay kernel (the propagator) is the impact of one trade trades later, independent of the others.
mx_prop.kernel_study.