 Pelatih
A return feature is a security’s compounded return over a window ending at or before the decision time, used as a predictor. Its skip period is the gap between the window’s end and the decision time: a 12-1 momentum feature uses the return from 252 to 21 trading days ago, skipping the last 21.
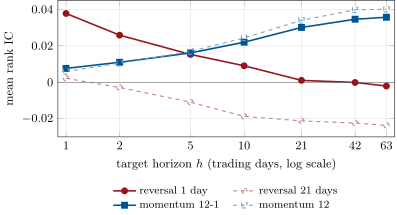
firm.synthmkt, seed 1.