
Alle boeken

Professioneel

Apps Over Coach Inloggen Begin met lezen

Quantitative Finance · Begrippenlijst

Wat is Return feature, skip period?

Ook bekend als: return feature · skip period

Definition 7.1 Research Craft: Predictors, Backtests, Measurement, Portfolios · Hoofdstuk 7 — Price and Volume Features

A return feature is a security’s compounded return over a window ending at or before the decision time, used as a predictor. Its skip period is the gap between the window’s end and the decision time: a 12-1 momentum feature uses the return from 252 to 21 trading days ago, skipping the last 21.
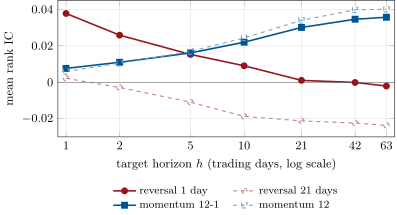
Mean rank IC of four return features against returns over the next h days on the synthetic market, scored every day. The one-day reversal peaks at a day and is gone after two weeks; the last month’s reversal is negative at every horizon (the month continues); momentum rises to about 0.04 at a quarter, slightly higher without the skip. Data: firm.synthmkt, seed 1.
Figure 7.1. Mean rank IC of four return features against returns over the next hh days on the synthetic market, scored every day. The one-day reversal peaks at a day and is gone after two weeks; the last month’s reversal is negative at every horizon (the month continues); momentum rises to about 0.04 at a quarter, slightly higher without the skip. Data: firm.synthmkt, seed 1.
Lees in het hoofdstuk →