
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Reverse cliquet؟

Definition 16.7 Derivatives and Volatility · الفصل 16 — Asians, Lookbacks, Cliquets and Forward-Starts

A reverse cliquet pays a large coupon eroded by every negative period return: max⁡(0, C+∑imin⁡(ri,0))\max\bigl(0,\,C+\sum_i\min(r_i,0)\bigr). The investor is short a strip of forward-start puts, capped in total.
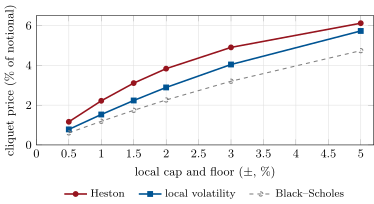
A one-year monthly cliquet (local cap and floor ± c, global floor zero) under three models that fit the one-year at-the-money call, and two that fit the whole surface. The narrower the local cap, the more the payoff is a string of forward digitals and the more the forward skew, not today’s smile, sets the price. Data: the tutorial.
Figure 16.4. A one-year monthly cliquet (local cap and floor ±c\pm c, global floor zero) under three models that fit the one-year at-the-money call, and two that fit the whole surface. The narrower the local cap, the more the payoff is a string of forward digitals and the more the forward skew, not today’s smile, sets the price. Data: the tutorial.

أمثلة

Example 16.8 (The cliquet that fits every vanilla)

A one-year cliquet with monthly periods pays the sum of the twelve monthly returns, each clipped to [−1%,+1%][-1\%,+1\%], floored at zero overall. On 100 000 paths with zero rates it is worth 1.53% of notional under local volatility, 2.22% under Heston and 1.19% under Black–Scholes at the one-year at-the-money volatility. All three fit the one-year at-the-money call, and the two smile models fit the whole surface. The Heston price is 45% above the local-volatility price. The gap widens as the local cap narrows and the payoff looks more like a digital: at ±0.5%\pm0.5\% the prices are 0.78% and 1.16%. A reverse cliquet paying max⁡(0,25%+∑min⁡(ri,0))\max(0,25\%+\sum\min(r_i,0)) is worth 5.43% under local volatility, 7.56% under Heston and 3.57% under Black–Scholes (Figure 16.4).

اقرأ في الفصل →