 Pelatih
A reverse cliquet pays a large coupon eroded by every negative period return: . The investor is short a strip of forward-start puts, capped in total.
Contoh
Example 16.8 (The cliquet that fits every vanilla)
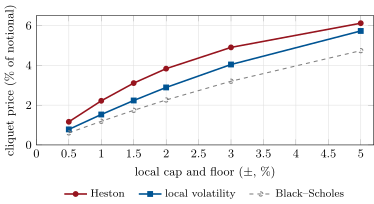
A one-year cliquet with monthly periods pays the sum of the twelve monthly returns, each clipped to , floored at zero overall. On 100 000 paths with zero rates it is worth 1.53% of notional under local volatility, 2.22% under Heston and 1.19% under Black–Scholes at the one-year at-the-money volatility. All three fit the one-year at-the-money call, and the two smile models fit the whole surface. The Heston price is 45% above the local-volatility price. The gap widens as the local cap narrows and the payoff looks more like a digital: at the prices are 0.78% and 1.16%. A reverse cliquet paying is worth 5.43% under local volatility, 7.56% under Heston and 3.57% under Black–Scholes (Figure 16.4).