
सभी किताबें

पेशेवर

ऐप्स परिचय Coach लॉग इन पढ़ना शुरू करें

Quantitative Finance · शब्दावली

Reverse cliquet क्या है?

Definition 16.7 Derivatives and Volatility · अध्याय 16 — Asians, Lookbacks, Cliquets and Forward-Starts

A reverse cliquet pays a large coupon eroded by every negative period return: max⁡(0, C+∑imin⁡(ri,0))\max\bigl(0,\,C+\sum_i\min(r_i,0)\bigr). The investor is short a strip of forward-start puts, capped in total.
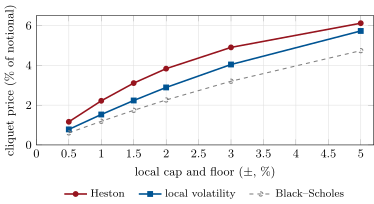
A one-year monthly cliquet (local cap and floor ± c, global floor zero) under three models that fit the one-year at-the-money call, and two that fit the whole surface. The narrower the local cap, the more the payoff is a string of forward digitals and the more the forward skew, not today’s smile, sets the price. Data: the tutorial.
Figure 16.4. A one-year monthly cliquet (local cap and floor ±c\pm c, global floor zero) under three models that fit the one-year at-the-money call, and two that fit the whole surface. The narrower the local cap, the more the payoff is a string of forward digitals and the more the forward skew, not today’s smile, sets the price. Data: the tutorial.

उदाहरण

Example 16.8 (The cliquet that fits every vanilla)

A one-year cliquet with monthly periods pays the sum of the twelve monthly returns, each clipped to [−1%,+1%][-1\%,+1\%], floored at zero overall. On 100 000 paths with zero rates it is worth 1.53% of notional under local volatility, 2.22% under Heston and 1.19% under Black–Scholes at the one-year at-the-money volatility. All three fit the one-year at-the-money call, and the two smile models fit the whole surface. The Heston price is 45% above the local-volatility price. The gap widens as the local cap narrows and the payoff looks more like a digital: at ±0.5%\pm0.5\% the prices are 0.78% and 1.16%. A reverse cliquet paying max⁡(0,25%+∑min⁡(ri,0))\max(0,25\%+\sum\min(r_i,0)) is worth 5.43% under local volatility, 7.56% under Heston and 3.57% under Black–Scholes (Figure 16.4).

अध्याय में पढ़ें →