Semua buku

Profesional

Aplikasi Tentang Pelatih Masuk Mulai membaca

Quantitative Finance · Glosarium

Apa itu Singular control, reflected Brownian motion?

Dikenal juga sebagai: singular control · reflected Brownian motion

Definition 10.9 Quantitative Methods · Bab 10 — Optimal Stopping and Impulse Control

A singular control acts through a process of finite variation that increases only on a set of times of Lebesgue measure zero. Reflected Brownian motion on [−b,b][-b, b] is X=σW+L−UX = \sigma W + L - U, with LL and UU nondecreasing, increasing only when X=−bX = -b and X=bX = b respectively: the minimal pushing that keeps XX in the interval.

Optimal band against the size of the trading cost, on log scales: with a fixed fee per ticket the band grows like the fourth root of the fee, with a proportional cost like the cube root. A hundredfold change in cost moves the bands by factors of 3.2 and 4.6. Data: closed forms, the chapter’s tutorial.
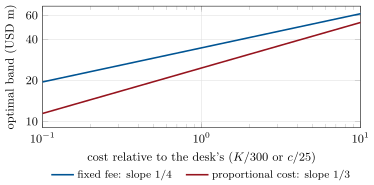
Figure 10.4. Optimal band against the size of the trading cost, on log scales: with a fixed fee per ticket the band grows like the fourth root of the fee, with a proportional cost like the cube root. A hundredfold change in cost moves the bands by factors of 3.2 and 4.6. Data: closed forms, the chapter’s tutorial.
Baca dalam konteks →