 Coach
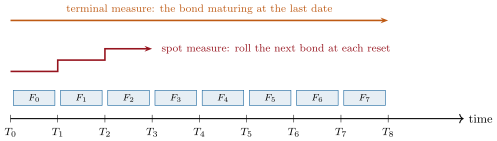
The spot measure of a tenor structure has as numeraire the discretely rebalanced bank account , which holds the bond maturing at the next reset date and rolls into the next one at each reset. The terminal measure is the forward measure of the last payment date , with numeraire .
Ejemplos
Example 8.8 (Caplets come back)
Ten annual forwards from chapter 2’s euro OIS curve (1.98% for the first year rising to 3.03% for the tenth), caplet volatilities of 70 basis points normal converted to Black (33.0% at one year down to 23.1% at nine), Rebonato’s function with the parameters of Figure 8.1 and correlation : 20 000 paths under the spot measure, four steps a year, reprice the at-the-money caplets to within two standard errors (Figure 8.3).