सभी किताबें

पेशेवर

ऐप्स परिचय Coach लॉग इन पढ़ना शुरू करें

Quantitative Finance · शब्दावली

Spot measure, terminal measure क्या है?

अन्य नाम: spot measure · terminal measure

Definition 8.6 Rates, Credit, XVA and Risk · अध्याय 8 — Forward-Rate and Market Models

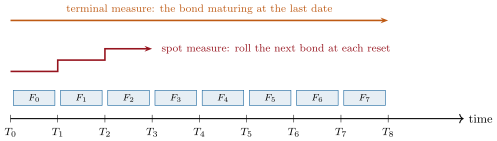
The spot measure Qd\mathbb Q^d of a tenor structure has as numeraire the discretely rebalanced bank account Bd(t)=P(t,Tm(t))∏j<m(t)(1+δjFj(Tj))B_d(t) = P(t,T_{m(t)})\prod_{j<m(t)}(1+\delta_jF_j(T_j)), which holds the bond maturing at the next reset date Tm(t)T_{m(t)} and rolls into the next one at each reset. The terminal measure is the forward measure of the last payment date TnT_n, with numeraire P(t,Tn)P(t,T_n).

A tenor structure of eight annual forwards and the numeraires of the two common simulation measures. Under the spot measure each forward’s drift sums over the forwards between the next reset and itself; under the terminal measure, over those after it.
Figure 8.2. A tenor structure of eight annual forwards and the numeraires of the two common simulation measures. Under the spot measure each forward’s drift sums over the forwards between the next reset and itself; under the terminal measure, over those after it.

उदाहरण

Example 8.8 (Caplets come back)

Ten annual forwards from chapter 2’s euro OIS curve (1.98% for the first year rising to 3.03% for the tenth), caplet volatilities of 70 basis points normal converted to Black (33.0% at one year down to 23.1% at nine), Rebonato’s function with the parameters of Figure 8.1 and correlation ρij=e−0.1∣i−j∣\rho_{ij}=e^{-0.1|i-j|}: 20 000 paths under the spot measure, four steps a year, reprice the at-the-money caplets to within two standard errors (Figure 8.3).

अध्याय में पढ़ें →