Tous les livres

Professionnel

Applis À propos Coach Connexion Commencer la lecture

Quantitative Finance · Glossaire

Qu'est-ce que « Trade price impact » ?

Definition 5.2 Microstructure and Execution · Chapitre 5 — Decomposing the Spread

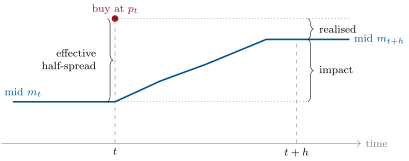
The trade price impact of a trade at horizon hh is εt(mt+h−mt)\varepsilon_t(m_{t+h}-m_t): the move of the mid in the trade’s direction over the next hh. The realised half-spread is εt(pt−mt+h)\varepsilon_t(p_t-m_{t+h}), what the provider would earn by closing her position at the later mid, and trade by trade
εt(pt−mt)⏟effective=εt(pt−mt+h)⏟realised+εt(mt+h−mt)⏟impact.\underbrace{\varepsilon_t(p_t-m_t)}_{\text{effective}}=\underbrace{\varepsilon_t(p_t-m_{t+h})}_{\text{realised}}+\underbrace{\varepsilon_t(m_{t+h}-m_t)}_{\text{impact}}.
One buy, split in two. The effective half-spread is what the buyer paid over the mid; after h, the part the mid has moved in the trade’s direction is the impact, the part left to the liquidity provider is the realised spread.
Figure 5.1. One buy, split in two. The effective half-spread is what the buyer paid over the mid; after hh, the part the mid has moved in the trade’s direction is the impact, the part left to the liquidity provider is the realised spread.
Lire dans le chapitre →
