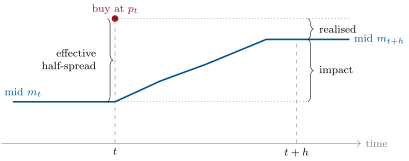
The trade price impact of a trade at horizon is : the move of the mid in the trade’s direction over the next . The realised half-spread is , what the provider would earn by closing her position at the later mid, and trade by trade
 Coach
लॉग इन
पढ़ना शुरू करें
Quantitative Finance · शब्दावली
The trade price impact of a trade at horizon is : the move of the mid in the trade’s direction over the next . The realised half-spread is , what the provider would earn by closing her position at the later mid, and trade by trade