 Coach
A bucketed sensitivity of a position is the change in its value when the -th input quote of the curve rises by one basis point and the curve is recalibrated, the others held. The risk ladder is the vector over all inputs; its sum is the sensitivity to a parallel shift of the quotes, and its dot product with a vector of quote moves (in basis points) is the first-order P&L, .
Examples
Example 3.2 (The desk’s ladder)
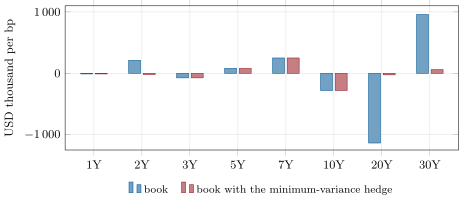
The chapter’s book holds 200 swaps of random maturity, direction and size (seeded), plus a two-year payer of USD 1.471 billion and a thirty-year payer of USD 281 million added so that the parallel DV01 is zero. Its ladder (Figure 3.1) is anything but zero: at two years, at seven, at ten, at twenty and at thirty, per basis point.