Alle boeken

Professioneel

Apps Over Coach Inloggen Begin met lezen

Quantitative Finance · Begrippenlijst

Wat is Bucketed sensitivity, risk ladder?

Ook bekend als: bucketed sensitivity · risk ladder

Definition 3.1 Rates, Credit, XVA and Risk · Hoofdstuk 3 — Rates Risk

A bucketed sensitivity Δk\Delta_k of a position is the change in its value when the kk-th input quote of the curve rises by one basis point and the curve is recalibrated, the others held. The risk ladder is the vector (Δ1,…,Δn)(\Delta_1,\dots,\Delta_n) over all inputs; its sum is the sensitivity to a parallel shift of the quotes, and its dot product with a vector of quote moves δq\delta q (in basis points) is the first-order P&L, P&L≈∑kΔk δqk\pnl\approx\sum_k\Delta_k\,\delta q_k.

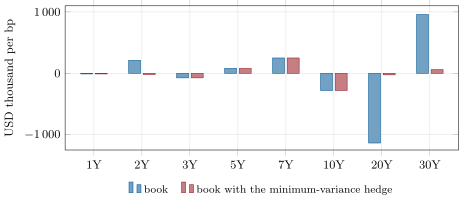
The risk ladder of the chapter’s 200-swap book, whose buckets sum to zero, and the ladder after the three-swap hedge of  (two-, twenty- and thirty-year swaps). The hedge does not zero those three buckets; it leaves the combination of risks that historical moves make cheapest to carry. Data: the chapter’s illustrative book and tutorial.
Figure 3.1. The risk ladder of the chapter’s 200-swap book, whose buckets sum to zero, and the ladder after the three-swap hedge of Example 3.11 (two-, twenty- and thirty-year swaps). The hedge does not zero those three buckets; it leaves the combination of risks that historical moves make cheapest to carry. Data: the chapter’s illustrative book and tutorial.

Voorbeelden

Example 3.2 (The desk’s ladder)

The chapter’s book holds 200 swaps of random maturity, direction and size (seeded), plus a two-year payer of USD 1.471 billion and a thirty-year payer of USD 281 million added so that the parallel DV01 is zero. Its ladder (Figure 3.1) is anything but zero: +212 010+212\,010 at two years, +249 817+249\,817 at seven, −279 791-279\,791 at ten, −1 135 816-1\,135\,816 at twenty and +958 308+958\,308 at thirty, per basis point.

Lees in het hoofdstuk →