جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Bucketed sensitivity, risk ladder؟

يُعرف أيضًا باسم: bucketed sensitivity · risk ladder

Definition 3.1 Rates, Credit, XVA and Risk · الفصل 3 — Rates Risk

A bucketed sensitivity Δk\Delta_k of a position is the change in its value when the kk-th input quote of the curve rises by one basis point and the curve is recalibrated, the others held. The risk ladder is the vector (Δ1,…,Δn)(\Delta_1,\dots,\Delta_n) over all inputs; its sum is the sensitivity to a parallel shift of the quotes, and its dot product with a vector of quote moves δq\delta q (in basis points) is the first-order P&L, P&L≈∑kΔk δqk\pnl\approx\sum_k\Delta_k\,\delta q_k.

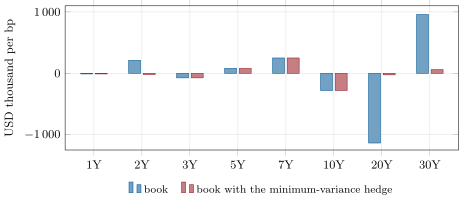
The risk ladder of the chapter’s 200-swap book, whose buckets sum to zero, and the ladder after the three-swap hedge of  (two-, twenty- and thirty-year swaps). The hedge does not zero those three buckets; it leaves the combination of risks that historical moves make cheapest to carry. Data: the chapter’s illustrative book and tutorial.
Figure 3.1. The risk ladder of the chapter’s 200-swap book, whose buckets sum to zero, and the ladder after the three-swap hedge of Example 3.11 (two-, twenty- and thirty-year swaps). The hedge does not zero those three buckets; it leaves the combination of risks that historical moves make cheapest to carry. Data: the chapter’s illustrative book and tutorial.

أمثلة

Example 3.2 (The desk’s ladder)

The chapter’s book holds 200 swaps of random maturity, direction and size (seeded), plus a two-year payer of USD 1.471 billion and a thirty-year payer of USD 281 million added so that the parallel DV01 is zero. Its ladder (Figure 3.1) is anything but zero: +212 010+212\,010 at two years, +249 817+249\,817 at seven, −279 791-279\,791 at ten, −1 135 816-1\,135\,816 at twenty and +958 308+958\,308 at thirty, per basis point.

اقرأ في الفصل →