
All books

Professional

Apps About Coach Log in Start reading

Quantitative Finance · Glossary

What is Cross-currency basis swap, cross-currency basis?

Also known as: cross-currency basis swap · cross-currency basis

Definition 16.6 Markets II: Rates, FX and Credit · Chapter 16 — FX Swaps, Forwards and the Cross-Currency Basis

A cross-currency basis swap exchanges notionals in two currencies at the start at the spot rate, exchanges floating interest in each currency during its life, one leg with a spread, and re-exchanges the same notionals at maturity. The spread is the cross-currency basis bb, quoted on the non-dollar leg; for short tenors it is measured from FX swaps as the gap between the yen (or euro) rate implied by forward points and the cash rate:
b  =  (FS (1+rbτb)−1)1τq−rq.b \;=\; \left(\frac{F}{S}\,(1 + r_b\tau_b) - 1\right)\frac{1}{\tau_q} - r_q.
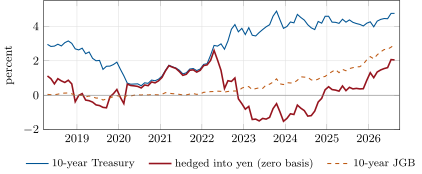
A ten-year Treasury for a yen investor, April 2018 to August 2026: unhedged, hedged by rolling short-dated FX swaps with no basis (the Treasury yield less SOFR plus the Japanese call rate), and the ten-year JGB. Any negative basis lowers the hedged line further. Month-end Treasury yields and SOFR, monthly averages for Japan. Data: FRED series DGS10, SOFR, IRSTCI01JPM156N and IRLTLT01JPM156N.
Figure 16.3. A ten-year Treasury for a yen investor, April 2018 to August 2026: unhedged, hedged by rolling short-dated FX swaps with no basis (the Treasury yield less SOFR plus the Japanese call rate), and the ten-year JGB. Any negative basis lowers the hedged line further. Month-end Treasury yields and SOFR, monthly averages for Japan. Data: FRED series DGS10, SOFR, IRSTCI01JPM156N and IRLTLT01JPM156N.
Read in context →