
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Cross-currency basis swap, cross-currency basis؟

يُعرف أيضًا باسم: cross-currency basis swap · cross-currency basis

Definition 16.6 Markets II: Rates, FX and Credit · الفصل 16 — FX Swaps, Forwards and the Cross-Currency Basis

A cross-currency basis swap exchanges notionals in two currencies at the start at the spot rate, exchanges floating interest in each currency during its life, one leg with a spread, and re-exchanges the same notionals at maturity. The spread is the cross-currency basis bb, quoted on the non-dollar leg; for short tenors it is measured from FX swaps as the gap between the yen (or euro) rate implied by forward points and the cash rate:
b  =  (FS (1+rbτb)−1)1τq−rq.b \;=\; \left(\frac{F}{S}\,(1 + r_b\tau_b) - 1\right)\frac{1}{\tau_q} - r_q.
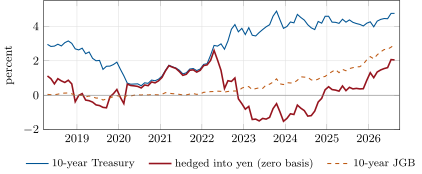
A ten-year Treasury for a yen investor, April 2018 to August 2026: unhedged, hedged by rolling short-dated FX swaps with no basis (the Treasury yield less SOFR plus the Japanese call rate), and the ten-year JGB. Any negative basis lowers the hedged line further. Month-end Treasury yields and SOFR, monthly averages for Japan. Data: FRED series DGS10, SOFR, IRSTCI01JPM156N and IRLTLT01JPM156N.
Figure 16.3. A ten-year Treasury for a yen investor, April 2018 to August 2026: unhedged, hedged by rolling short-dated FX swaps with no basis (the Treasury yield less SOFR plus the Japanese call rate), and the ten-year JGB. Any negative basis lowers the hedged line further. Month-end Treasury yields and SOFR, monthly averages for Japan. Data: FRED series DGS10, SOFR, IRSTCI01JPM156N and IRLTLT01JPM156N.
اقرأ في الفصل →