Coach
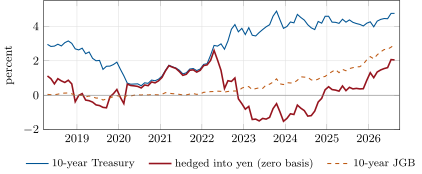
A cross-currency basis swap exchanges notionals in two currencies at the start at the spot rate, exchanges floating interest in each currency during its life, one leg with a spread, and re-exchanges the same notionals at maturity. The spread is the cross-currency basis , quoted on the non-dollar leg; for short tenors it is measured from FX swaps as the gap between the yen (or euro) rate implied by forward points and the cash rate: