 Coach
The default risk charge captures the jump-to-default risk of credit and equity positions that spread shocks miss. The residual risk add-on charges a flat share of notional for risks the sensitivities do not capture: 1% for instruments with exotic underlyings, 0.1% for other residual risks.
Examples
Example 23.6 (The standardised charge of the book)
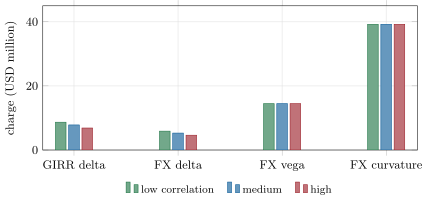
Chapter 21’s book, on 23 September 2026. Its GIRR sensitivities (mapping the two bonds’ par-yield sensitivities to the two- and ten-year USD tenors, a simplification) are and dollars per basis point; with risk weights and and a correlation of 88.7%, the GIRR delta charge is USD 7.83 million. FX delta (EUR and JPY, risk weight , cross-currency correlation 60%) is USD 5.30 million; FX vega, the straddle’s vega times its 8% volatility at a 100% risk weight, USD 14.49 million; FX curvature, from shocking EURUSD by , USD 39.23 million. In the low correlation scenario the total is USD 68.29 million, the largest of the three (Figure 23.1).