Tous les livres

Professionnel

Applis À propos Coach Connexion Commencer la lecture

Quantitative Finance · Glossaire

Qu'est-ce que « Factor model » ?

Definition 22.8 Quantitative Methods · Chapitre 22 — Covariance Estimation and Random Matrices

A factor model of covariance is Σ=BFB⊤+D\Sigma = BF B^\top + D, with k≪Nk \ll N factor exposures BB, a factor covariance FF and a diagonal specific variance DD; statistical factor models take BB from the leading principal components of SS.

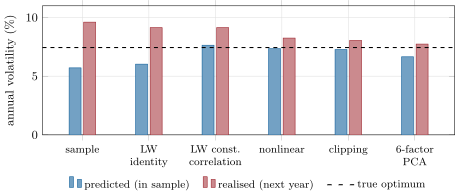
Minimum-variance portfolios of 200 stocks from six covariance estimates on two years of daily returns: the volatility each predicts and the volatility each delivers over the next year, averaged over fifty simulated histories; the dashed line is the true minimum, 7.44%. Data: the chapter’s tutorial, seeded.
Figure 22.4. Minimum-variance portfolios of 200 stocks from six covariance estimates on two years of daily returns: the volatility each predicts and the volatility each delivers over the next year, averaged over fifty simulated histories; the dashed line is the true minimum, 7.44%. Data: the chapter’s tutorial, seeded.
Lire dans le chapitre →