Todos los libros

Profesional

Apps Acerca de Coach Iniciar sesión Empezar a leer

Quantitative Finance · Glosario

¿Qué es Spiked covariance model?

Definition 22.4 Quantitative Methods · Capítulo 22 — Covariance Estimation and Random Matrices

In the spiked covariance model (Johnstone, 2001) the population covariance is the identity except for a few eigenvalues ℓ1,…,ℓk>1\ell_1, \dots, \ell_k > 1, the spikes, standing for factors above a noise floor.
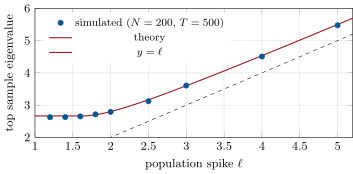
The spike transition: the largest sample eigenvalue against a single population spike  (all other eigenvalues one), with the theory: the bulk edge (1 + √ q)2 = 2.66 below the threshold 1 + √ q = 1.63, and (1 + q/( - 1)) above it. Data: the chapter’s tutorial, seeded.
Figure 22.3. The spike transition: the largest sample eigenvalue against a single population spike ℓ\ell (all other eigenvalues one), with the theory: the bulk edge (1+q)2=2.66(1 + \sqrt q)^2 = 2.66 below the threshold 1+q=1.631 + \sqrt q = 1.63, and ℓ(1+q/(ℓ−1))\ell(1 + q/(\ell - 1)) above it. Data: the chapter’s tutorial, seeded.
Leer en el capítulo →
