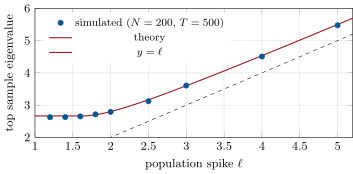
In the spiked covariance model (Johnstone, 2001) the population covariance is the identity except for a few eigenvalues , the spikes, standing for factors above a noise floor.
 Coach
Inloggen
Begin met lezen
Quantitative Finance · Begrippenlijst
In the spiked covariance model (Johnstone, 2001) the population covariance is the identity except for a few eigenvalues , the spikes, standing for factors above a noise floor.